Investment intelligence · Colombia first
The future
starts with
fundamentals.
Research Colombian listed companies with in-depth financial analysis, clear explanations, and identifiable sources.
Understand the businesses behind the numbers.
In development · Private access
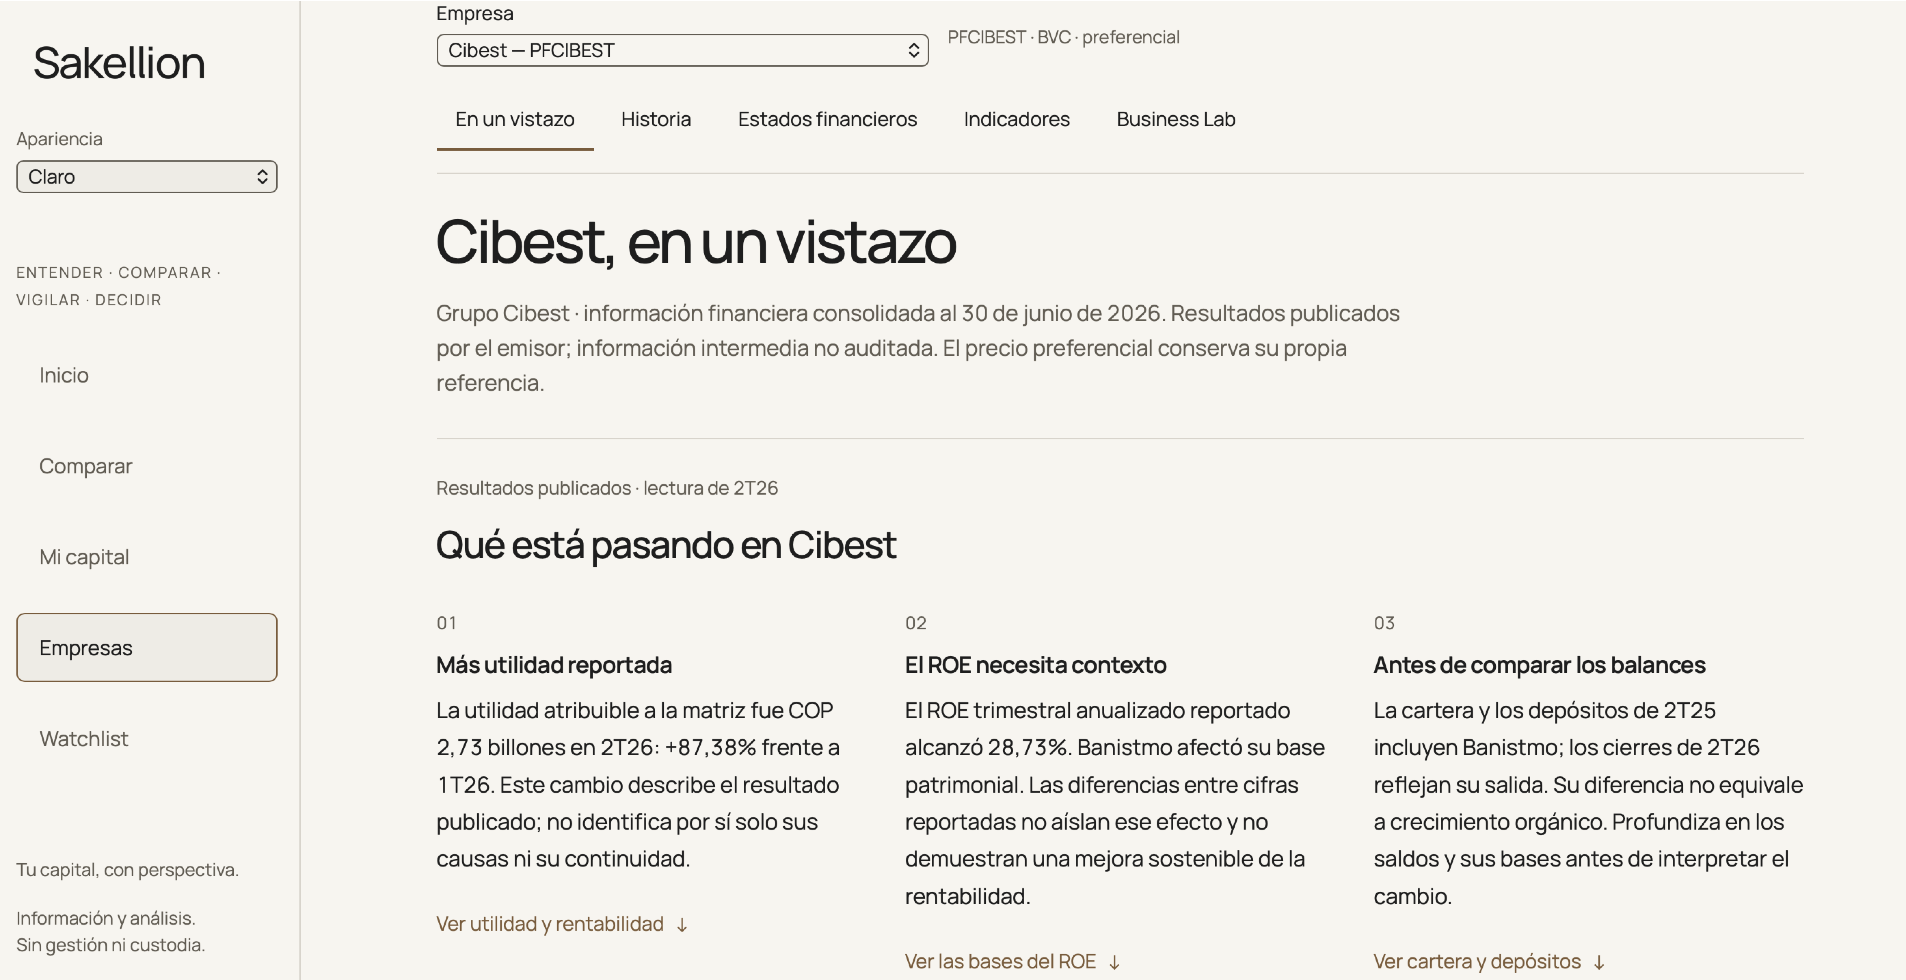
Spanish interface. Unaudited interim consolidated information. Historical screenshot, not a live view.
A real company.
A closer look.
From the reported result to context and evidence.
An editorial example; no affiliation with the issuer.
01 / Look beyond the figure
One number never
tells the whole story.
Higher profit does not, by itself, explain how the business has changed. Understanding the result takes reporting periods, business context and evidence.
- Information across different disclosures.
- Results that need interpretation.
- Metrics that need context.
02 / Sakellion Lens
Does higher profit mean
a stronger business?
A guided look at Cibest. Open each step to move from the figure to its context and source.
Editorial reading · Cibest
Change in net income attributable to the parent’s shareholders
+87.38%
2Q26 versus 1Q26 · Grupo Cibest consolidated
Quarter-on-quarter change. Unaudited interim results.
A reported change, not an investment conclusion.
Source: 2Q26 results · Form 6-KThe figureWhat changed?
Net income attributable to the parent’s shareholders increased from the previous quarter. The figure describes a result; it does not, by itself, explain the causes or show whether they will persist.
| Period | Net income attributable to parent shareholders |
|---|---|
| 1Q26 | 1,457,111 |
| 2Q26 | 2,730,344 |
The contextWhat deserves a closer look?
The report records the sale of Banistmo and changes in equity. Examine the basis of ROE before interpreting profitability; a single factor should not explain every change.
Higher reported profit does not, on its own, demonstrate a sustainable improvement in the business.
The sourceWhere can you check it?
Read the issuer’s consolidated results summary. Keep quarterly results separate from closing balances and read the notes before making comparisons.
- Issuer
- Grupo Cibest S.A.
- Period
- Quarter ended June 30, 2026
- Document
- August 2026 Form 6-K · 2Q26 results
Historical example · Quarter ended June 30, 2026. Unaudited interim consolidated information. The change is a percentage; the report’s tables use COP millions. The report includes pro forma comparisons: check that basis before using the screenshot’s balances. This is not a recommendation on Cibest.
03 / Your research journey
Start with the business.
Go deeper into the numbers.
Move from the company overview to its financial statements, keeping the context in view.
At a glanceUnderstand what is happening in the business.
Start with the main results and a financial narrative that highlights what changed and what deserves a closer look.
See the real product viewIn perspectiveExplore metrics and their evolution.
Investigate available history and indicators, with reporting periods and the limits of each comparison kept visible.
Financial statementsGet closer to the numbers.
Explore income statements, balance sheets and cash flows within each company’s available coverage.
Available experiences, metrics and financial history vary by company and source coverage.
04 / Our approach
Numbers need context.
They also need sources.
- Visible periods
- See which date or interval a figure describes. A quarter, a year-to-date result and a closing balance tell different stories.
- Business context
- Keep acquisitions, business disposals and accounting changes in view when they may affect a comparison.
- Identifiable evidence
- Return to available, verified sources to check the result and understand its limits.
Sakellion provides information and analytical tools. It does not provide personalized investment advice or guarantee outcomes.
05 / Meet Sakellion
Research with
greater clarity.
We are building Sakellion for investors who want to understand the companies behind their investments.
Currently in private access.
Request a private walkthroughYour request goes directly to the founder by email. Walkthroughs are arranged personally; this is not registration or a promise of immediate access.
[email protected]